What international payment processing actually means
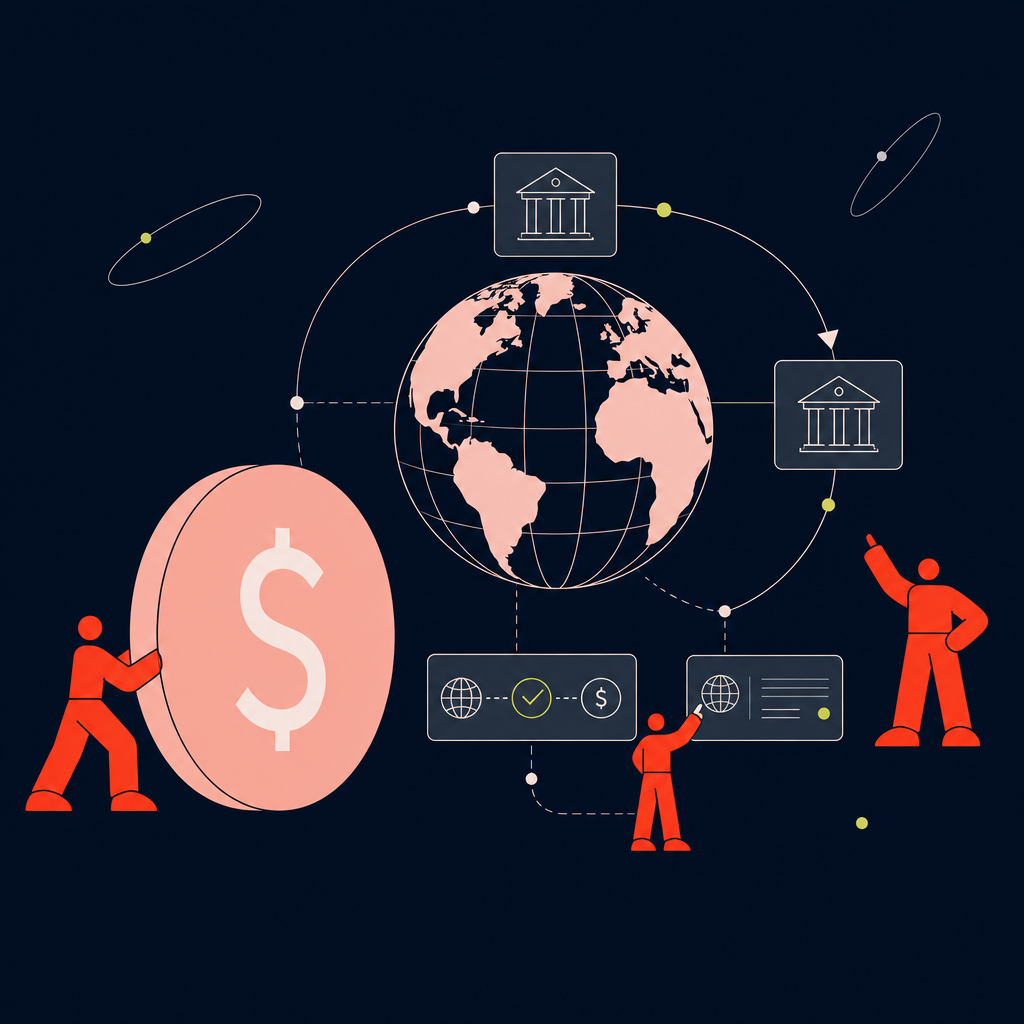
International payment processing is the network of systems and procedures that transfers funds from a corporate bank account to an overseas recipient by executing currency conversions, routing transactions through banking rails, and verifying settlement. For companies with recurring global contractor operations, this process functions as a continuous operating cycle demanding strict financial control and compliance.
Most finance teams still view cross-border payments through the lens of individual wire transfers. That mental model functions adequately when managing five contractors across two countries, but it fails when scaling to 150 contractors across a dozen jurisdictions. At that volume, the primary operational burden shifts from initiating transfers to executing the prerequisite compliance checks, currency conversions, invoice reconciliations, and payment status tracking required before and after funds move.
Every pay cycle introduces mandatory compliance screening, foreign exchange (FX) conversions, invoice reconciliation, and contractor inquiry handling. Looking at an isolated wire transfer hides these operational overheads. Establishing a repeatable payment processing system ensures workforce visibility, audit readiness, and cost control across every payment run.
Why a single cross-border payment breaks down at scale
A single cross-border payment breaks down at scale because every intermediate step, from the originating bank through intermediary institutions to currency conversion and final settlement, adds processing delays, transaction fees, and reconciliation friction. As contractor volume expands into hundreds of monthly payments, these compounding manual touchpoints turn routine disbursements into a major operational cost.
Here is how a single payment moves through international channels:
- The originating bank debits the sender account and routes payment instructions to the destination country.
- One or more intermediary banks relay the transfer, applying processing fees and extending delivery timelines.
- Foreign exchange conversion converts sender currency to beneficiary currency using rates assigned by the executing institution.
- The receiving bank verifies beneficiary account details and credits the recipient, subject to local compliance checks.
Each handling step can delay settlement by full business days and erode payment amounts through hidden FX spreads and correspondent banking fees, typically ranging from 15 to 40 USD per transfer on the Society for Worldwide Interbank Financial Telecommunication (SWIFT) network. While tolerable for isolated payments, managing hundreds of monthly transfers without localized rails forces organizations to absorb unaccounted fees, spikes support inquiries, and degrades workforce visibility until bank reconciliations close weeks later.
The four things that make or break recurring contractor payments
Executing recurring contractor payments efficiently depends on four core operational capabilities: automated recurring compliance checks, transparent foreign exchange cost management, batch processing for mass payouts, and real-time payment status tracking. Mastering these elements allows finance teams to maintain strict financial control and workforce visibility while preventing operational bottlenecks during peak payout cycles.
Compliance and KYC checks that repeat every cycle
Know Your Customer (KYC) and sanctions screening require continuous verification rather than a single onboarding approval. Banking partners re-verify beneficiary details periodically, meaning updated bank accounts, altered legal structures, or address changes can pause transfers mid-cycle. Automated systems track compliance status continuously across jurisdictions, preventing payment failures and protecting the organization from non-compliance liability.
FX cost and intermediary bank fees
Net payout amounts vary based on which institution executes the currency conversion and how many intermediary banks handle the transfer. Identical payments sent on the same date can yield different final amounts depending on the routing path taken. Without centralized tracking of FX spreads and transfer fees, finance teams lose visibility into the true cost of global disbursements.
Payment groups and batching for mass payouts
Grouping contractors by currency, destination country, or payout schedule converts hundreds of individual transactions into consolidated batch executions. Processing payments individually multiplies administrative workload and increases exposure to per-transaction banking fees. Batching standardizes payout runs and guarantees predictable land date execution for recipient workforces.
Payment-status visibility and reconciliation
Finance teams require immediate visibility into cleared, pending, and failed transactions to maintain financial control without waiting for contractor inquiries. Manual reconciliation against separate bank statements and invoice ledgers introduces administrative latency and human error. Automated status tracking links payment outputs directly to accounting ledgers for immediate audit readiness.
Key terms Finance needs before evaluating a provider
Evaluating international payment processing providers requires an understanding of core banking terminology, payment rail mechanics, and routing structures. A clear understanding of terms like SEPA, FX spreads, intermediary bank fees, and smart routing enables finance leaders to accurately assess provider capabilities, hidden transaction costs, and operational compliance features.
Wondering how cross-border payment operations plays out in your countries?
A Papaya specialist can map this to your actual workforce instead of the general case.
- Single Euro Payments Area (SEPA): A regional payment scheme that enables euro-denominated transfers between participating European countries using standardized, low-cost clearing mechanisms instead of correspondent wire networks.
- Intermediary bank: A correspondent institution that routes funds between originating and receiving banks when no direct relationship exists, charging handling fees and adding processing time.
- FX spread: The margin between wholesale interbank foreign exchange rates and the retail rate applied to a currency conversion, serving as a primary source of indirect transaction cost.
- Payment gateway: A software integration layer that initiates, routes, and monitors digital payments, providing a unified management interface across multiple global banking rails.
- Smart routing: Automated decision logic that evaluates payment parameters, including currency, destination, and transfer value, to select the fastest and most cost-effective processing path.
- Mass payments: The execution of multiple payout instructions to diverse international beneficiaries within a single consolidated batch run.
- Payment in advance: The pre-funding of a payment account or batch prior to execution, ensuring funds are cleared and available immediately upon release.
How SEPA and regional rails change the math for European contractors
Single Euro Payments Area (SEPA) and localized payment rails significantly reduce cross-border transaction costs and transfer delays by bypassing intermediary correspondent banks. Routing transfers through local clearing networks allows organizations to execute euro payments with predictable settlement schedules, reduced processing fees, and improved financial control across European contractor workforces.
SEPA transfers clear through standardized European clearinghouses, delivering predictable processing times and avoiding correspondent bank deductions. However, SEPA functionality is limited to euro payments within member states. Operating across non-euro countries like the UK or non-European jurisdictions requires managing multiple regional rails alongside traditional wire systems.
Manually categorizing payouts to match appropriate clearing rails introduces operational risk as workforce count grows. Determining whether a payment qualifies for local rails versus international wires requires dedicated automated logic during every payout run. For detailed mechanics on structuring euro disbursements, review how SEPA payments work for contractor payouts specifically.
What smart routing and automated reconciliation solve that manual processes can't
Smart routing and automated reconciliation eliminate the manual operational burden of selecting payment paths and matching transaction records. Smart routing automatically selects the optimal, lowest-cost clearing rail for every transfer, while automated reconciliation matches outgoing disbursements directly to internal invoices, ensuring continuous audit readiness and operational scalability.
Smart routing software evaluates destination parameters, transaction volume, and currency pairings in real time to direct payments through local clearing networks or global banking partners. Automated reconciliation then validates completed payouts against open invoices and ledger entries, isolating exceptions for manual review. Combined, these technologies remove repetitive administrative tasks from monthly payment cycles.
This technical capability marks the shift from basic commercial banking portals to dedicated global payment infrastructure. While manual file uploads and bank portals suffice for managing a few contractors, managing high-volume global pay runs across dozens of currencies requires automated routing and reconciliation to maintain financial control. To examine how intelligent payment pathways function operationally, read this guide to payment smart routing for global operations.
What it looks like when the operating model actually works
A modernized international payment operating model replaces fragmented banking relationships with a unified processing architecture, drastically reducing administrative overhead and transfer costs. Consolidating multi-entity disbursement workflows into a single system establishes consistent compliance controls, predictable land dates, and complete workforce visibility across all operating regions.
South Pole previously managed payroll and contractor disbursements across 27 legal entities using 15 separate local payroll providers. This decentralized structure forced regional teams to handle compliance checks, bank funding, and ledger reconciliation independently across disparate systems.
After centralizing disbursements onto Papaya Global's platform, South Pole reported more than 600 hours of manual work saved per week and about EUR 417K in annual savings. These operational gains resulted from replacing 15 fragmented workflows with a single, standardized disbursement system handling compliance, funding, and reconciliation.
For growing enterprises, the primary financial return comes not from minor FX rate adjustments, but from removing redundant manual processes across recurring payment runs. Eliminating administrative touchpoints gives finance leadership total financial control and audit readiness across international operations.
How to evaluate a provider against your recurring payment cycle
Evaluating an international payment provider requires assessing operational performance across recurring payout workflows rather than isolated transaction demos. Finance teams must test provider capabilities against compliance automation, transparent foreign exchange pricing, multi-currency batch processing, and live payment status tracking to ensure long-term operational scalability.
Geographic and currency coverage must support both current operations and planned expansion. For example, Papaya Global supports workforce coverage across 180+ countries, allowing organizations to onboard talent in new jurisdictions without building new banking infrastructure or contracting local providers.
When assessing potential payment platform partners, evaluate these specific operational requirements:
- Does the system perform automated KYC and compliance re-verification on a recurring schedule across all active jurisdictions?
- Can payouts be grouped and executed in consolidated batches by currency, country, or schedule?
- Does the platform deliver real-time payment status tracking for both finance administrators and recipient contractors?
- Is per-transaction FX pricing and intermediary fee breakdown visible prior to batch execution?
A corporate payment infrastructure must satisfy all four criteria to support recurring global contractor disbursements effectively. Evaluating platforms on these operational capabilities ensures the organization maintains audit readiness, compliant operations, and financial control.
Turning this into your next payment cycle, not just a one-off fix
Establishing efficient international payment processing requires transitioning from reactive transaction management to a structured, repeatable operating model. Many finance teams still treat each cross-border payment run as its own event: chasing new compliance documentation, re-checking currency rates, and manually matching records after the fact. That pattern works for a handful of payments but breaks down once volume, currency count, or headcount grows. Standardizing compliance checks, currency routing, batch processing, and reconciliation into a consolidated platform gives ongoing financial control, transparent transaction costs, and consistent payment schedules across global operations. Once these steps run on a fixed cycle rather than an ad hoc basis, finance teams know in advance what a payment run will cost and when funds will land, instead of discovering both after the transfer has already gone out.
Organizations achieving long-term efficiency in global disbursements focus on system integration rather than individual transaction rates. Shopping for the lowest FX rate on each transfer feels like cost control, but it ignores the larger cost: every time a payment desk re-quotes a rate or re-verifies a payee, it repeats compliance and reconciliation work that a standardized platform would otherwise run once per cycle. Consolidating compliance, FX management, batch execution, and accounting reconciliation into a unified operational cycle removes that manual friction and gives finance teams full visibility into where every payment stands, which employees have been paid, and which transactions still require review. That visibility matters most during audits or year-end reporting, when gaps in a manual process are hardest to reconstruct.
The gap between a workflow that looks efficient and one that actually holds up under audit, scale, or currency volatility often isn't visible until a payment run goes wrong. To evaluate your current cross-border payout workflows against enterprise standards, download our free checklist to choose the right international payment processor at papayaglobal.com/payments-platform. Use it to compare how your existing process handles compliance verification, FX routing, batch timing, and reconciliation against what a consolidated platform would do in a single, repeatable cycle.
Frequently asked questions
How should I evaluate mass payment capabilities before signing with a provider?
Evaluate whether the platform supports automated batch processing by currency, destination country, or payout schedule rather than requiring individual transfer execution. Confirm direct regional coverage: Papaya Global supports workforce coverage across 180+ countries, providing established banking rails across active and prospective talent markets.
How can I automate recurring contractor payments instead of processing them manually each cycle?
Automating recurring payments involves grouping contractors into defined payout pools by currency or schedule, funding batches through pre-funded payment accounts, and using automated compliance routing. This structure removes manual data entry, guarantees consistent land date execution, and eliminates repetitive administrative tasks.
What should I look for in a corporate payment solution if I pay contractors in multiple countries?
Select a solution that automates multi-jurisdiction compliance screening, provides transparent per-transaction FX pricing, and supports mass payout batching. A platform limited to single-country clearing forces manual workarounds as your international footprint expands.
How can I reduce cross-border payment complexity as my contractor base grows?
Reduce operational complexity by consolidating individual payout actions into currency-based batch runs and automating recurring KYC verifications. Standardizing payout logic maintains predictable administrative workloads even as workforce headcount and geographic distribution increase.
When do I actually need a multi-currency payment gateway versus a regular bank account?
Commercial bank accounts manage low-volume transfers in limited currencies effectively. However, as disbursements expand across multiple currencies and jurisdictions, the administrative burden of manual routing, FX tracking, and invoice reconciliation requires dedicated payment gateway logic to preserve financial control and audit readiness.
Is payment in advance ever appropriate in my contractor payment workflow?
Pre-funding payment runs is effective for high-volume batch disbursements because it allows batch release immediately upon approval without transaction funding delays. This approach relies on real-time visibility into pending payout batches to ensure funds remain fully controlled and properly allocated.
The next step is cross-border payment operations in your own setup
Bring your countries, worker mix and payment cycles to a Papaya specialist and get a straight answer on what changes.