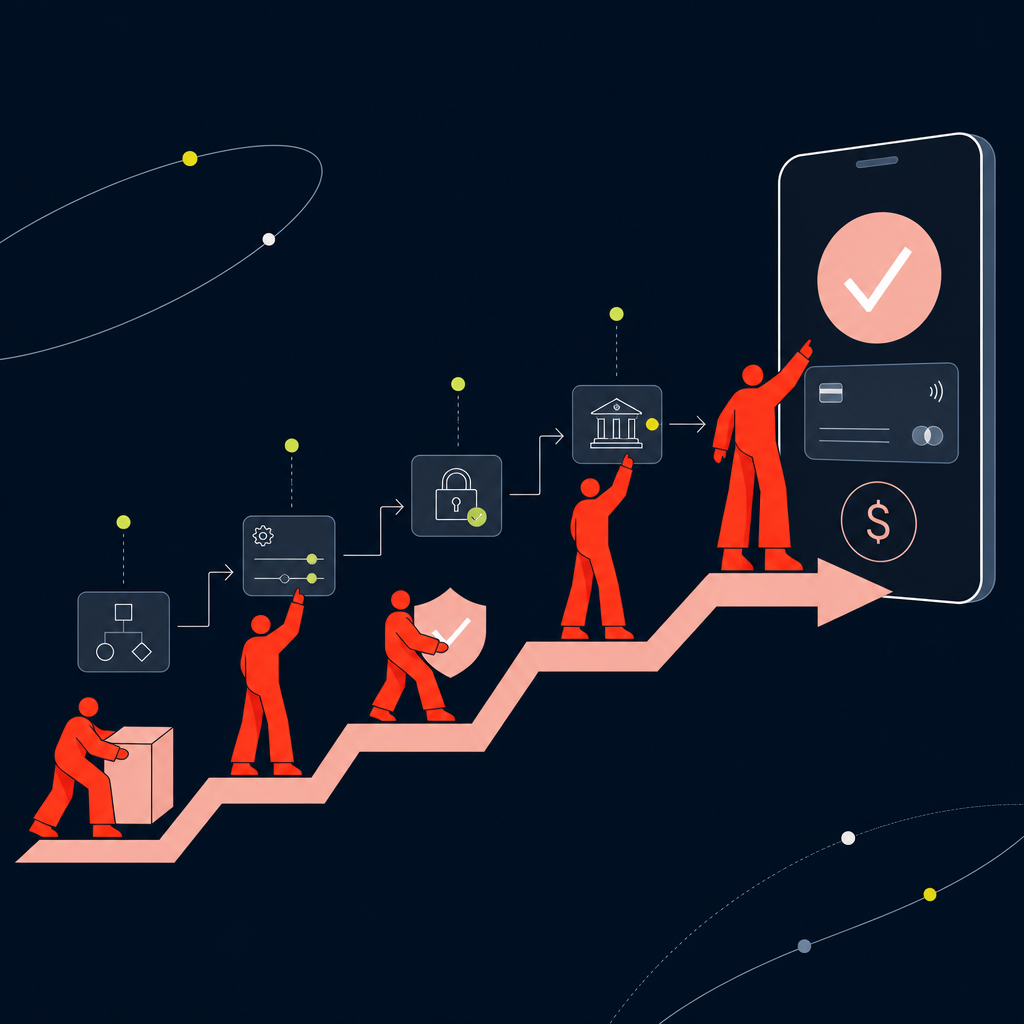
Setting up electronic payment systems for international contractors requires replacing disconnected banking portals and manual spreadsheet runs with a unified, automated payment pipeline that preserves financial control and eliminates cross-border friction. Building this infrastructure allows finance teams to aggregate incoming invoices, verify worker identities, group payments by currency rail, and execute multi-currency disbursements without manual intervention. Replacing fragmented wire uploads with structured automation cuts administrative overhead and gives finance leaders real-time workforce visibility over international payouts.
Why standard bank portals fail international contractor cycles
Standard bank portals fail recurring contractor cycles because they require manual data transfers, lack native multi-currency routing, and provide zero real-time tracking across international banking networks. Finance teams wasting hours on manual comma-separated values (CSV) uploads experience delayed disbursements, hidden intermediary correspondent fees, and severe reconciliation friction that degrades contractor trust and inflates administrative overhead.
Traditional corporate banking interfaces were built for localized, low-frequency transactions rather than high-volume contractor networks. When finance operations manage dozens of international workers across different jurisdictions, manually copying wire details into isolated banking portals introduces human error and security risks. In 2023, data showed that 69% of US online adults used a digital payment method for transactions, reflecting a broad shift toward modernized digital rails that corporate banking systems have struggled to match.
Relying on legacy bank tools leaves finance managers blind to transfer progress once funds leave the originating account. Corrupted routing codes, unexpected intermediary bank deductions, and delayed foreign exchange (FX) conversions frequently cause payment drops that require manual research. Migrating to dedicated electronic payment systems replaces these opaque banking runs with direct, programmatic payout flows that guarantee predictable execution dates.
Prerequisites for building an automated contractor payment pipeline
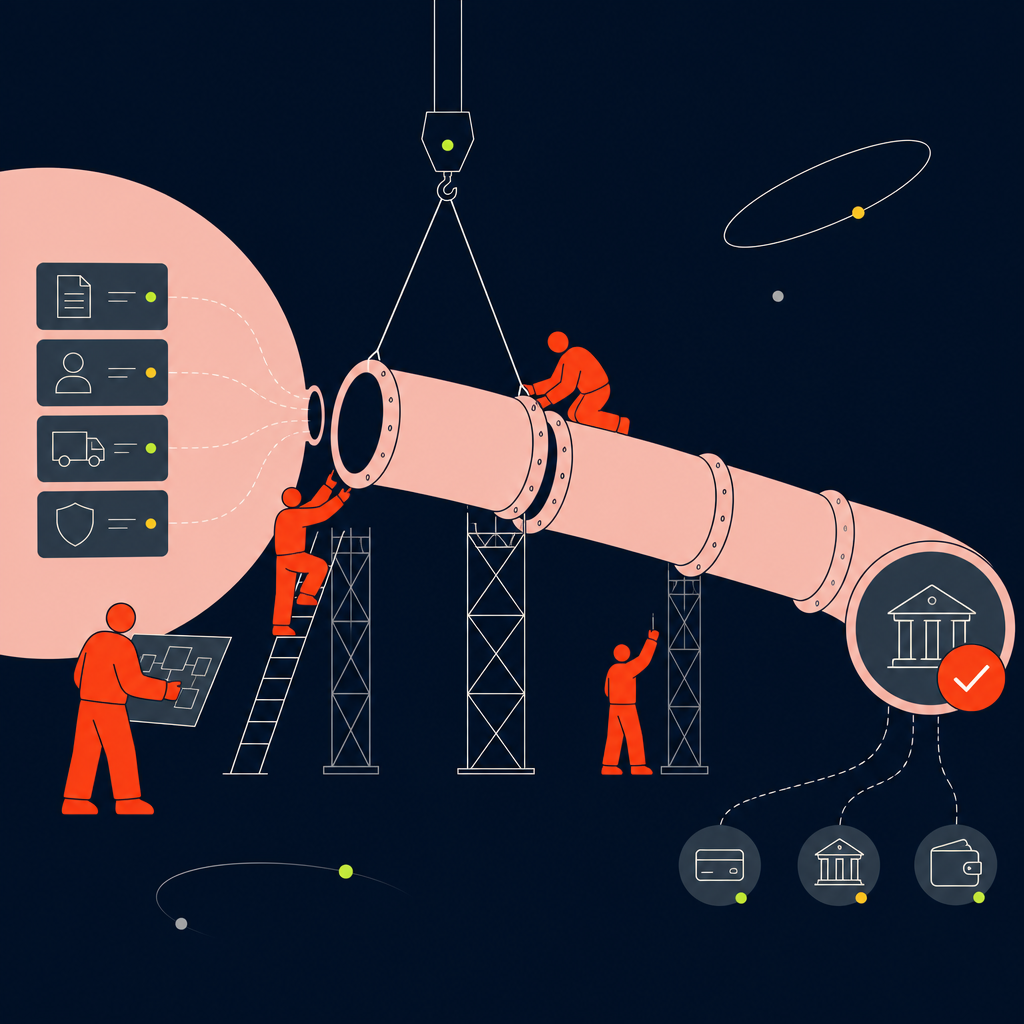
Building an automated contractor payment pipeline requires centralized worker tax forms, validated local bank account details, multi-currency funding accounts, and an automated invoice intake workflow. Establishing these foundational elements ensures compliance verification and payout routing can occur programmatically before any funds are moved, preventing payout failures and manual payroll holds.
Before automating your payment execution, you must gather the core structural components and worker verification data. Moving from physical checks or manual transfers to digital workflows creates immediate operational gains. Research indicates that digital payment channels are less expensive for businesses compared to traditional cash payments while providing higher transfer speeds and reduced administrative burden.
To construct a resilient payment architecture, finance departments must assemble five core inputs:
- Completed tax identity documentation, such as W-8BEN or W-9 forms, linked directly to each contractor profile to manage compliance risk.
- Verified local clearing data, including SWIFT (the global bank messaging network) codes, International Bank Account Number (IBAN) details, and local routing information confirmed through account validation tools.
- Multi-currency holding accounts or virtual wallets capable of holding target currencies to avoid forced spot conversions.
- Standardized contractor agreements defining net payment terms, currency preferences, and approval hierarchies.
- An integrated invoice ingestion interface that extracts billing amounts and matches them to active contracts.
Securing these components upfront eliminates payment holds caused by incomplete banking information. Digital payment infrastructure remains faster and safer to collect and verify than manual paper documentation, enabling finance teams to run batch verification checks automatically prior to every scheduled payout cycle.
Step 1: Standardize KYC, invoice collection, and payout rules
Standardizing identity checks and invoice collection involves establishing a single digital portal where contractors upload identity documents, tax forms, and structured invoices. Automating pre-payment validation rules ensures every invoice matches contract terms and compliance requirements before finance approves the payout, completely eliminating manual spreadsheet checks.
With prerequisites established, the first step is standardizing incoming contractor data and compliance checks. Finance teams cannot automate payments if incoming invoice data arrives through unstructured channels like email attachments or chat threads. Establishing mandatory data standards ensures that every payout request enters the payment engine formatted correctly.
Automating identity validation and invoice intake
Contractors must submit their invoices through a centralized portal that enforces required fields, such as invoice numbers, service descriptions, line-item breakdowns, and tax IDs. The platform validates these submissions against active contracts, checking that billing rates and total hours align with agreed parameters. Concurrently, automated Know Your Customer (KYC) protocols verify worker identity documents and screen names against global sanctions lists.
By enforcing compliance rules upstream, finance managers prevent unvetted contractors or invalid invoices from entering the approval queue. Using a dedicated contractor payment platform allows teams to automate these validation gates, ensuring that only verified invoices advance to payout grouping.
Step 2: Group payments by currency rail and fund balances efficiently
Grouping payments by currency rail involves aggregating approved invoices into specific payout batches based on target currency and geographic clearing networks. Funding these batches through local clearing rails or pre-funded multi-currency accounts bypasses SWIFT correspondent banks, reducing foreign exchange markup and eliminating intermediary transfer fees.
Once contractor invoices and compliance are validated, you must optimize how funds are routed and funded across currencies. Executing individual international transfers for every approved invoice results in compounding wire fees and unpredictable FX spreads. Grouping payouts transforms fragmented disbursements into concentrated, cost-effective funding events.
Structuring payment groups and currency routing
Finance managers should group approved payouts into currency-specific batches, such as EUR clearing via Single Euro Payments Area (SEPA), GBP payouts via Faster Payments, and USD payouts via Automated Clearing House (ACH). Instead of initiating cross-border wires from a single domestic account, the payment system routes funds to local distribution hubs or uses pre-funded multi-currency balances. This approach cuts intermediary correspondent bank charges (which often run between 15 and 40 USD per transfer) and locks in transparent FX conversion rates prior to disbursement.
Optimizing currency rails ensures contractors receive their exact invoiced amounts on time without unexpected bank deductions. Electronic payment systems make recurring payouts easier to collect across digital networks, allowing companies to maintain total control over liquidity while minimizing foreign exchange drag.
Step 3: Execute automated payouts and establish live status visibility
Executing automated payouts requires releasing pre-funded payment groups through programmatic payment rails (the local networks that move money) while generating live tracking links for finance and contractors. Providing full status visibility allows workers to monitor transaction milestones while finance teams maintain direct audit trails for general ledger reconciliation.
After funding the target currency pools, you can execute the batch payouts and activate real-time tracking. Modern workforce operations depend on predictable payout timelines to maintain contractor engagement. In consumer payment trends, PayPal was used by 40% of US online adults in 2023 for transactions, demonstrating worker expectations for familiar, instant digital channels.
Delivering status tracking and automated execution
Similarly, adoption of alternative payment rails has expanded rapidly; for example, Apple Pay adoption more than doubled since 2019 to reach 24% of online adults. When business payment systems incorporate automated local rails and digital wallet integrations, international contractors receive funds directly into their preferred local accounts without multi-day delays.
Once batch payouts execute, the system generates real-time status updates for every transaction. Finance teams can track payment stages from pending to settled, while contractors receive automated notifications confirming delivery. Implementing Papaya Global provides centralized governance over these execution cycles, giving finance leaders complete control over multi-country worker payments across 180+ countries.
Troubleshooting cross-border payment failures and reconciliation drag
Troubleshooting payment failures requires establishing automated exception alerts, maintaining dedicated buffer accounts for fee adjustments, and enforcing standardized bank code validation. Resolving account details before payout execution and using automated general ledger integration eliminates manual reconciliation drag and prevents recurring transfer failures across international banking corridors.
Even with an automated pipeline running, operational exceptions like banking delays and routing failures require structured troubleshooting protocols. Cross-border banking involves complex correspondent networks where minor data errors can cause payment rejections. Finance teams must deploy systemic remedies rather than handling failures case by case.
Resolving common operational exceptions
Finance teams frequently encounter three primary operational bottlenecks during international payouts:
- Intermediary fee deductions: Correspondent banks often deduct transfer charges from the principal amount. Fix this by using local payment rails or selecting guaranteed OUR fee structure instructions where the sender absorbs transfer costs.
- Incorrect account details: Invalid IBANs or SWIFT codes trigger payment rejections. Fix this by implementing pre-validation application programming interface (API) checks at the time of contractor onboarding to block incorrect details before batch execution.
- General ledger reconciliation drag: Manual entry of multi-currency bank fees creates balance sheet discrepancies. Fix this by integrating electronic payment systems directly with your enterprise resource planning (ERP) system to auto-reconcile payouts upon settlement.
Establishing an automated exception workflow ensures rejected payments trigger immediate alerts to both finance operators and contractors. Relying on specialized software like Papaya Global's workforce payments platform ensures that currency conversions and batch settlements flow directly into your accounting system to maintain audit readiness without requiring manual journal entries.
Achieving total finance control over recurring contractor cycles
Achieving total finance control over recurring contractor cycles means replacing fragmented manual processes with an automated payout engine. This operational maturity delivers complete visibility over cash flow, transparent FX pricing, automated compliance verifications, and predictable payout schedules that strengthen international workforce relationships.
Resolving operational edge cases brings your payment operations to complete maturity. When finance teams automate contractor verification, invoice ingestion, currency grouping, and settlement tracking, recurring payout runs transition from an operational burden to a strategic capability. Organizations running global contractor models gain exact predictability over payment execution timelines and international transfer costs.
Building scalable infrastructure for contractor payouts allows your organization to expand into new markets without increasing administrative headcount. By centralizing payment execution through modern electronic payment systems, finance leaders maintain strict regulatory compliance while delivering a superior talent experience to global contractors.
Implement secure e-payments now: start your guided setup.
Frequently asked questions
How can a company automate recurring international contractor payments?
Companies automate recurring contractor payments by connecting invoice intake systems directly to automated payment engines. Contractor profiles store verified bank details and tax forms, while incoming invoices trigger automated compliance checks. Once approved, invoices are batched into payment groups, routed through local currency rails, and reconciled automatically with general ledger software.
How do electronic payment systems handle multi-currency payments without high FX fees?
Electronic payment systems reduce FX fees by routing transactions through local clearing networks rather than international wire transfers. By pre-funding multi-currency accounts or batching payouts into localized currency pools, systems eliminate correspondent bank fees and access wholesale foreign exchange rates, avoiding high retail bank spreads on cross-border transactions.
How should Finance evaluate electronic payment systems for a distributed contractor workforce?
Finance should evaluate payment systems based on payment control, cost transparency, currency coverage, and ERP integration capabilities. Key factors include the platform's ability to automate KYC verification, group payments by currency rail, provide real-time status tracking, and deliver clean reconciliation data without requiring manual administrative intervention.
What should a secure electronic payment system include for cross-border compliance?
A secure electronic payment system must include automated identity verification, global sanctions screening, local tax document collection (such as W-8BEN forms), and encrypted bank account validation. Additionally, the system should offer strict role-based access controls, comprehensive audit logs, and secure data storage compliant with regional privacy regulations.
The next step is cross-border payment operations in your own setup
Bring your countries, worker mix and payment cycles to a Papaya specialist and get a straight answer on what changes.