What is the Single European Payment Area?
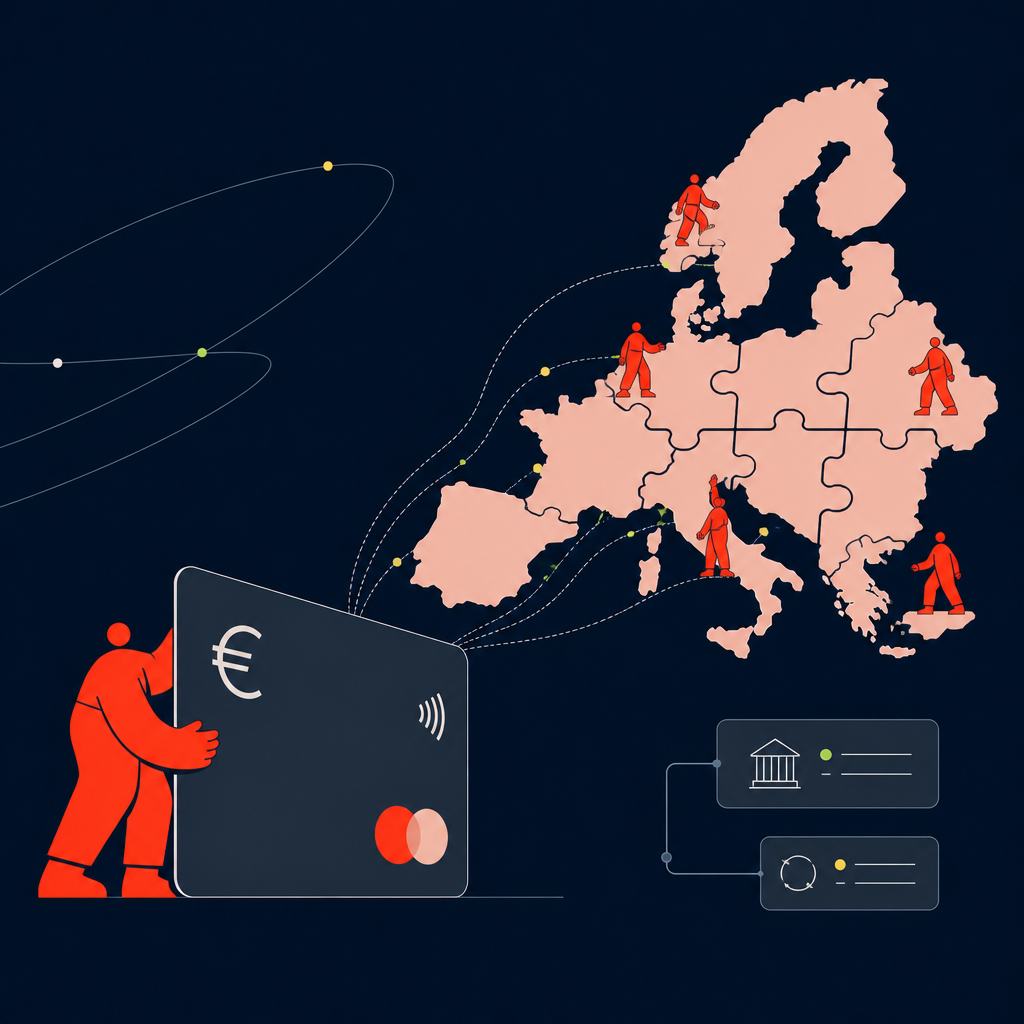
The Single European Payment Area (SEPA) is a standardized payment-integration framework that enables individuals and businesses to execute cashless euro bank transfers across participating European countries. By unifying payment rules, it allows organizations to pay beneficiaries in any member state from a single bank account using standard domestic conditions, fees, and processing speeds.
Finance teams often assume that expanding cross-border payouts across Europe requires opening local bank accounts in every target market or relying on expensive wire networks. The Single European Payment Area eliminates this operational drag by treating all euro-denominated transfers across participating countries as local transactions. According to official definitions from the European Union payment-integration system, SEPA was explicitly created to make cross-border bank transfers in euros as fast, cheap, and simple as domestic payments.
For companies running active contractor networks across Europe, this framework replaces fragmented local banking arrangements with a single execution model. A business registered in one member state can fund payouts to independent contractors in Germany, France, or Spain without maintaining local sub-accounts or negotiating regional banking agreements. Standardized rules govern how payment instructions are structured, processed, and cleared across national borders.
Through this architecture, European operations can rely on the principle that a euro transfer sent from Berlin to Lisbon carries the same legal weight and processing rules as a transfer sent across town. Under the underlying framework established for European banking, cashless euro transfers can be delivered to any account within the zone using a single bank account and an International Bank Account Number (IBAN), under the same basic conditions and charges as transfers within a domestic market.
Removing administrative hurdles between national payment systems simplifies treasury management for finance departments. Operational leaders no longer need to manage multiple corporate banking relationships or absorb variable cross-border fee schedules just to settle recurring invoices across European territories.
Key structural pillars of the unified European payment framework include:
- Standardized account numbering across all member territories via IBAN structures
- Harmonized execution rules for push transfers and direct debit collections
- Equalized fee structures that prohibit surcharge penalties on cross-border transactions
- Direct clearing settlement between participating commercial banks without intermediary deductions
Core mechanisms of SEPA bank transfers
Core mechanisms of SEPA bank transfers depend on standardized clearing rails, unified account identifiers, and European Union regulations that enforce fee equality and execution deadlines. Transfers rely on International Bank Account Numbers to route funds directly between financial institutions, eliminating intermediary routing fees and guaranteeing standardized clearing timeframes across all participating nations.
The mechanics of European transfers rely on strict regulatory alignment to ensure that cross-border payments move with the same predictability as domestic clearing systems. The primary purpose of this architecture is to build an integrated payment area to increase efficiency, reduce operational overhead, and enhance market competitiveness, particularly benefiting micro, small, and medium-sized enterprises across participating countries.
This regulatory backing is grounded in binding European legislation that governs how financial institutions process and clear transaction batches. Under Directive 2366/2015/EU adopted in 2015, the European Commission established the legal framework for payment services in the internal market, aiming to increase competition, open market access to non-bank payment providers, and harmonize consumer protections across member states.
Regulatory backing and consumer protections
The legal architecture behind European payments protects both funding institutions and payment recipients by standardizing transaction rights. Payment service providers operating within the zone must adhere to strict rules regarding execution timeframes, liability for unexecuted transactions, and transparency in fee disclosure.
These protections remove the uncertainty that historically plagued international wire transfers, where intermediate correspondent banks could deduct variable fees without advance notice. When finance teams issue payouts under this legal umbrella, the full face value of the payment reaches the target account, preventing invoice discrepancies and vendor friction.
Fee parity and standard execution windows
A central requirement of European payment regulations is fee parity, which mandates that banks cannot charge higher fees for cross-border euro transfers than they do for equivalent domestic transfers. If an enterprise bank account offers free domestic clearing, it must extend those same terms to transfers destined for any other country within the network.
Execution timelines are similarly standardized across all participating financial institutions. Standard credit transfers clear within one business day, while real-time instant schemes process within seconds, providing treasury managers with clear visibility over cash flow and funding schedules.
Key operational benefits of standardized execution include:
- Equalized transaction fees between domestic and cross-border euro payouts
- Guaranteed next-day or real-time settlement windows for clean cash forecasts
- Elimination of hidden correspondent banking deductions during transmission
- Direct account-to-account clearing using standardized IBAN address formatting
Key terms in European payment operations
Key terms in European payment operations encompass the standardized protocols and identifiers used to route and execute euro transactions. These terms include International Bank Account Numbers, Bank Identifier Codes, SEPA Credit Transfers, SEPA Instant Credit Transfers, and SEPA Direct Debits, which together define account formatting, transaction timing, and pull-or-push settlement methods.
Wondering how cross-border payment operations plays out in your countries?
A Papaya specialist can map this to your actual workforce instead of the general case.
Executing high-volume payouts across European markets requires precise technical protocols to govern account addressing and message passing. In 2009, European payment institutions expanded this ecosystem by launching the SEPA direct debit capability on October 13, establishing automated pull-based transactions across borders alongside traditional push transfers.
Understanding the distinction between push and pull payment mechanisms is essential when configuring automated finance operations. According to operational analysis shared on Hacker News discussion threads, SEPA payments can be pull-based, where a business debits an account after receiving authorization, alongside standard push transfers where funds are explicitly pushed by the payer.
Finance operations teams rely on several standard payment instruments and account structures across the zone:
- IBAN (International Bank Account Number): An internationally agreed structural standard consisting of up to 34 alphanumeric characters that uniquely identifies an individual bank account across national borders.
- BIC (Bank Identifier Code): Also known as a SWIFT (Society for Worldwide Interbank Financial Telecommunication) code, an 8- to 11-character code that identifies a specific financial institution within the global banking network.
- SCT (SEPA Credit Transfer): The standard push-payment rail used to send euro payments from one bank account to another within the zone, settling within one business day.
- SCT Inst (SEPA Instant Credit Transfer): An upgraded real-time payment scheme that executes and settles euro transfers in under ten seconds, operating 24 hours a day, 365 days a year.
- SDD (SEPA Direct Debit): A pull-payment scheme allowing authorized payees to automatically collect euro-denominated funds directly from a payer's bank account across participating nations.
Mastering these terms allows finance operations managers to build structured payment files that pass validation on the first attempt. Correct IBAN validation and instrument selection prevent payment returns and maintain consistent payout schedules for distributed teams.
Managing recurring contractor cycles within SEPA
Managing recurring contractor cycles within SEPA requires automating invoice intake, batching payment instructions into standardized XML files, and unifying cross-border clearing through a centralized payment workflow. By replacing individual bank logins with automated mass payouts, finance teams eliminate repetitive KYC checks, reduce currency conversion costs, and achieve clean automated reconciliation.
While European payment rails simplify the transmission of euros, finance teams supporting hundreds of independent contractors still face operational complexity. Running weekly or bi-weekly payout cycles across distributed international teams often involves manual invoice verification, repeated data entry across multiple online banking portals, and fragmented status tracking. For broader guidance on structuring cross-border workflows, see our cross border payment processing guide.
When scaling operations across several jurisdictions, managing independent local bank accounts or separate payroll channels quickly creates administrative overhead. Companies handling complex global structures often struggle with operational fragmentation; for instance, enterprise sustainability firm South Pole consolidated 27 legal entities and 15 payroll providers into one system to simplify administrative oversight.
Consolidating fragmented administrative operations directly yields measurable productivity gains and financial returns. In that same enterprise implementation, South Pole reported saving more than 600 hours of manual work per week while capturing approximately EUR 417,000 in annual cost savings by unifying global operations.
Eliminating local banking complexity across distributed entities
Without a centralized payment execution strategy, finance teams often open separate local bank accounts in every European country where they engage contractors. This multi-bank approach forces treasury staff to monitor varying balance minimums, manage localized user permissions, and perform separate daily statement reconciliations across several banking portals.
A unified European payout model allows finance departments to execute all regional payments from a primary treasury pool. By relying on standardized IBAN routing across the entire zone, operations teams can pay contractors in Germany, Portugal, or Finland directly without setting up local legal subsidiaries or local operational bank accounts.
Modern payment infrastructure platforms like Papaya Global consolidate these distributed workflows into a single operational interface. Finance teams can upload a single funding batch, validate account details automatically, and dispatch payments across multiple European countries while maintaining strict administrative controls and workforce visibility.
Operational friction eliminated by centralized payout architectures includes:
- Multiple bank login procedures and fragmented multi-factor authentications
- Manual data re-entry across separate national banking tools
- Discrepancies caused by local bank cutoff times and localized holiday schedules
- Decentralized account verification checks for new contractor onboarding
Automating batch funding and reconciliation for weekly cycles
High-volume contractor payouts require batch processing capabilities that replace manual entry with direct bank integration. By converting approved contractor invoices into standardized ISO 20022 XML (Extensible Markup Language) payment files, finance teams can execute hundreds of individual transfers in a single approved funding instruction.
Automated reconciliation connects payment execution directly back to general ledger accounting software. When batches settle across European clearing networks, transaction metadata, including exact fees, execution dates, and beneficiary reference codes, automatically maps to open invoices, eliminating manual month-end matching.
Key steps to operationalize weekly contractor payout cycles include:
- Standardizing contractor invoice intake and automated compliance verification upon submission
- Consolidating approved invoices into unified multi-beneficiary payment batches
- Validating beneficiary IBAN and BIC formatting prior to transmission to prevent execution bounces
- Funding execution batches through a single centralized corporate treasury account
- Automating line-item reconciliation between clearing confirmation files and general ledger accounts
Building a scalable European contractor payment model
Building a scalable European contractor payment model involves unifying contractor onboarding, invoice validation, multi-currency funding, and payment execution into a single, automated operating system. By using European payment rails within a centralized governance framework, finance teams ensure compliance, maintain complete workforce visibility, and eliminate manual treasury overhead as global contractor volume expands.
Standardized payment rails across Europe provide a solid foundation for scaling distributed operations without inflating administrative overhead. However, relying on payment rails alone leaves critical operational gaps around contractor onboarding, invoice generation, tax compliance, and automated treasury execution. Operational teams require an integrated approach to manage the complete lifecycle of independent service providers; explore our complete contractor payment platform guide to understand how software unifies these steps.
To achieve total financial control over recurring payment cycles, finance leaders must connect their core accounting and ERP (enterprise resource planning) systems directly to dedicated global payout infrastructure. Using platforms such as Papaya Global features allows enterprises to manage contractor engagement, automate compliance checks, execute mass payouts, and maintain audit readiness across 180+ countries.
By shifting from manual, fragmented banking tools to an automated payout platform, finance departments transform global contractor payments from an operational bottleneck into a repeatable, scalable advantage. Operations teams gain real-time status visibility over every transaction, ensuring contractors are paid reliably on their agreed land date while maintaining financial control and absorbing compliance risks.
Strategic advantages of an integrated global payment infrastructure include:
- Complete automation from contractor invoice approval to final bank clearing
- Real-time visibility into payout delivery status and treasury balances
- Complete financial controls with role-based access permissions and audit logs
- Scalable multi-currency funding options that absorb cross-border settlement risk
Understand SEPA: Simplify your European payments.
Frequently asked questions
How does the Single European Payment Area simplify cross-border contractor payouts?
The Single European Payment Area standardizes euro bank transfers across member countries, allowing companies to pay contractors in any participating nation from a single bank account using standard domestic conditions, low transfer fees, and uniform execution timelines.
How do SEPA Direct Debit and Credit Transfers differ for recurring payouts?
SEPA Credit Transfers are push payments where a company initiates and sends funds directly to a contractor's bank account, whereas SEPA Direct Debits are pull payments where an authorized business debits funds directly from a payer's bank account upon authorization.
How can Finance cut operational overhead on European contractor payment cycles?
Finance teams cut operational overhead by consolidating multi-country payments into centralized batch instructions, automating IBAN validation and invoice matching, and using unified global payment platforms to eliminate manual banking entry and multi-entity account management.
Can a business pay all European contractors from a single bank account?
Yes, under European payment integration regulations, a business can pay contractors located in any participating country from a single euro-denominated bank account using standardized IBAN identifiers without needing local entities or regional bank accounts.
The next step is cross-border payment operations in your own setup
Bring your countries, worker mix and payment cycles to a Papaya specialist and get a straight answer on what changes.